# chrono-ta
Timestamp-aware technical indicators for Rust.
[](https://github.com/austin-starks/chrono-ta/actions/workflows/ci.yml)
[](https://crates.io/crates/chrono-ta)
[](https://docs.rs/chrono-ta)
[](https://github.com/austin-starks/chrono-ta/blob/master/LICENSE)
[](https://www.rust-lang.org/)
`chrono-ta` computes moving averages, momentum, volatility, extrema, drawdown,
crossovers, true range, and VWAP over elapsed-time windows. Every streaming input carries a UTC
timestamp, so a 30-day indicator means 30 calendar days of observations rather
than the last 30 calls.
## Built for NexusTrade
`chrono-ta` is the technical-analysis engine used by
[NexusTrade](https://nexustrade.io/), Austin Starks's algorithmic-trading and
backtesting platform. NexusTrade is the reason this crate treats timestamps,
irregular observations, and repeated live updates as first-class behavior:
those are production data conditions, not optional edge cases.
The library remains independently useful and intentionally small, but its API
is exercised against NexusTrade's real integration path. Releases are protected
by fixed golden vectors, streaming-versus-batch parity checks, same-bucket
replacement tests, and serialized-state continuation tests.
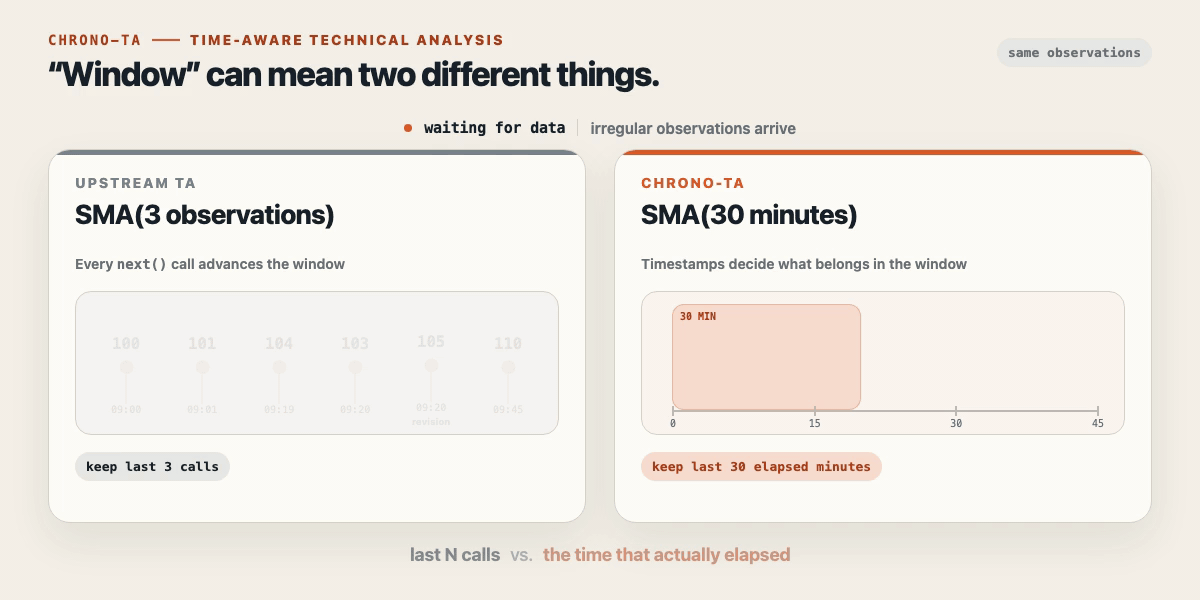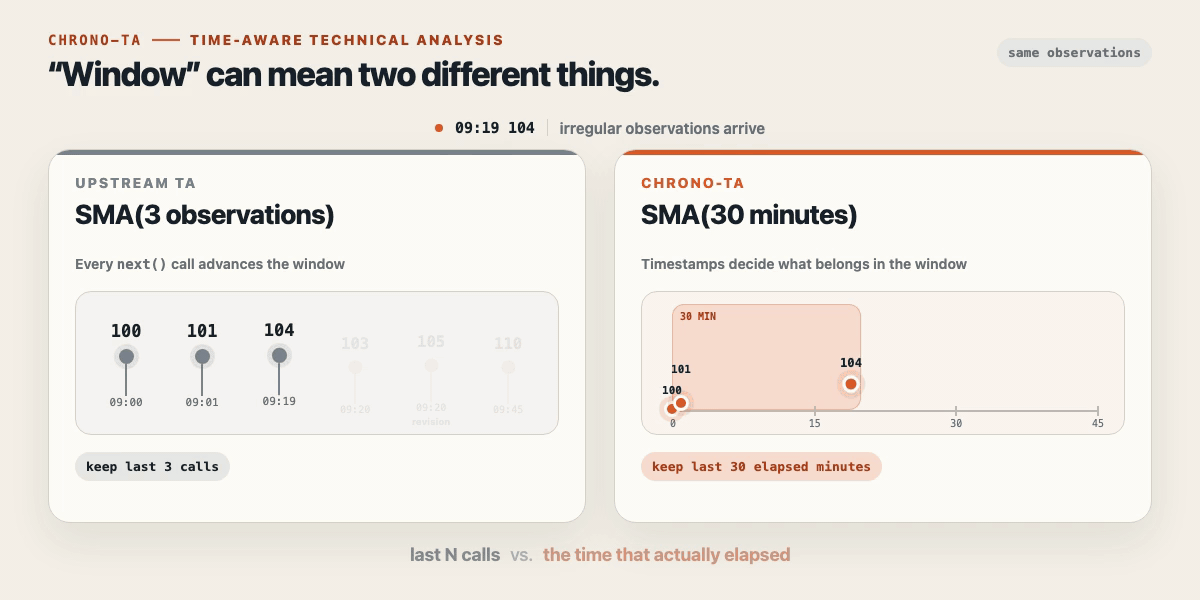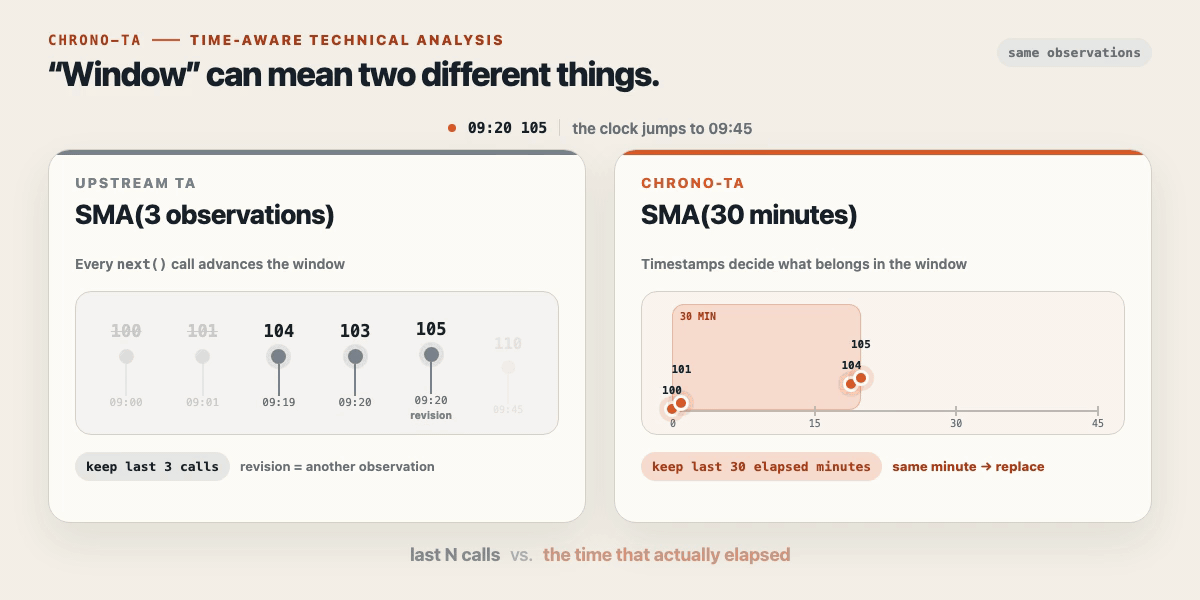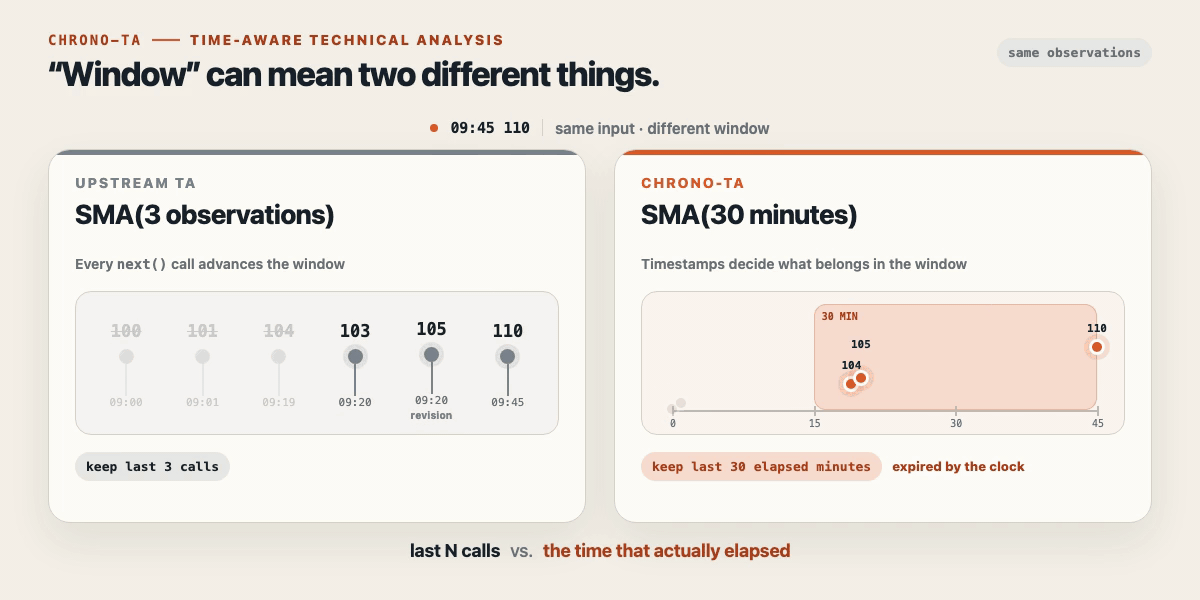
The animation uses the same irregular observations on both sides: upstream
`ta` retains the last N calls, while `chrono-ta` replaces a repeated time bucket
and expires observations according to elapsed time. Its reproducible Remotion
source lives in [`graphic/`](https://github.com/austin-starks/chrono-ta/tree/master/graphic).
The project began as a fork of [Greyblake's `ta`](https://github.com/greyblake/ta-rs),
but its input model and window semantics now differ substantially.
## Why this exists
Observation-count windows are useful when every series has a fixed cadence. In
market systems, the same strategy may instead receive daily bars, hourly bars,
irregular historical data, or repeated live updates to the current bar.
`chrono-ta` makes time part of the indicator contract:
```text
(timestamp, value) -> indicator -> value for that point in time
```
That enables:
- windows expressed as `std::time::Duration`;
- expiration based on timestamps rather than call count;
- replacement of repeated updates within the current time bucket;
- scalar streaming and batched processing through the same stateful API;
- SIMD-backed batch paths for EMA and RSI, with scalar parity tests;
- bounded storage for long-running windowed indicators.
## `chrono-ta` versus `ta`
These crates share ancestry, not a drop-in-compatible API.
| Window definition | Elapsed time, such as 15 minutes or 30 days | Number of observations, such as 14 values |
| Streaming input | `(DateTime<Utc>, value)` | A value or market-data item |
| Repeated live updates | Replaces the current time bucket | Every call advances state |
| Batch API | `NextBatch` plus public SIMD primitives | Scalar `Next` |
| Indicator scope | Focused set used by the timestamped engine | Broader classic indicator catalog |
| Install name | `chrono-ta` | `ta` |
| Rust import | `chrono_ta` | `ta` |
Choose upstream `ta` when you want its larger indicator catalog and
observation-count semantics. Choose `chrono-ta` when timestamps, elapsed-time
expiration, repeated current-bar updates, or batch processing are part of the
problem.
## Install
Install the published crate:
```toml
[dependencies]
chrono-ta = "2.2"
```
Enable serialization when indicator state must survive a restart:
```toml
[dependencies]
chrono-ta = { version = "2.2", features = ["serde"] }
```
To test an unreleased GitHub revision instead:
```toml
[dependencies]
chrono-ta = { git = "https://github.com/austin-starks/chrono-ta" }
```
## Quick start
```rust
use chrono::{Duration as ChronoDuration, TimeZone, Utc};
use chrono_ta::indicators::ExponentialMovingAverage;
use chrono_ta::Next;
use std::time::Duration;
let mut ema = ExponentialMovingAverage::new(Duration::from_secs(3 * 60)).unwrap();
let start = Utc.with_ymd_and_hms(2026, 9, 20, 14, 30, 0).unwrap();
assert_eq!(ema.next((start, 2.0)), 2.0);
assert_eq!(
ema.next((start + ChronoDuration::minutes(1), 5.0)),
3.5
);
assert_eq!(
ema.next((start + ChronoDuration::minutes(2), 1.0)),
2.25
);
```
All indicators implement `Next<T>`. They also implement `Reset`, `Debug`,
`Display`, `Default`, and `Clone` where appropriate.
## From market data to an automated strategy
`chrono-ta` owns indicator state and signal calculation. It deliberately does
not own market-data credentials, brokerage accounts, or order submission. A
trading application queries timestamped observations from its data provider,
feeds each completed bar into a strategy, and passes the resulting decision to
a separately guarded broker adapter.
### Query real market data
This example queries one-minute regular-session stock bars from Public's
[historical bars API](https://public.com/api/docs/resources/market-data/get-bars-v2-with-aggregation).
Need a Public account? You can open one through
[NexusTrade's Public referral link](https://public.com/nexustrade).
Generate a Public secret in your account settings, exchange it for an access
token using the [Public quickstart](https://public.com/api/docs/quickstart), and
keep the resulting token on the server as `PUBLIC_ACCESS_TOKEN`. Never put a
brokerage secret or access token in browser code.
Application dependencies (these are not required by `chrono-ta` itself):
```toml
[dependencies]
chrono = { version = "0.4", features = ["serde"] }
chrono-ta = "2.2"
reqwest = { version = "0.12", features = ["json", "rustls-tls"] }
serde = { version = "1", features = ["derive"] }
serde_json = "1"
tokio = { version = "1", features = ["macros", "rt-multi-thread"] }
uuid = { version = "1", features = ["v4"] }
```
```rust
use chrono::{DateTime, Utc};
use serde::Deserialize;
use std::{env, error::Error};
#[derive(Debug, Deserialize)]
struct Bar {
timestamp: DateTime<Utc>,
close: String,
}
#[derive(Default, Deserialize)]
struct MarketSession {
#[serde(default)]
bars: Vec<Bar>,
}
#[derive(Deserialize)]
#[serde(rename_all = "camelCase")]
struct BarsResponse {
regular_market: MarketSession,
}
async fn query_bars(
client: &reqwest::Client,
symbol: &str,
) -> Result<Vec<Bar>, Box<dyn Error>> {
let access_token = env::var("PUBLIC_ACCESS_TOKEN")?;
let url = format!(
"https://api.public.com/userapigateway/historicdata/EQUITY/{symbol}/DAY/ONE_MINUTE"
);
let response: BarsResponse = client
.get(url)
.bearer_auth(access_token)
.query(&[("tradingSessionToggle", "REGULAR_HOURS")])
.send()
.await?
.error_for_status()?
.json()
.await?;
Ok(response.regular_market.bars)
}
```
Public splits its response into pre-market, regular-market, and after-market
sections. This example deliberately asks for regular hours and consumes only
`regularMarket`; change that policy consciously because session selection
changes the observations that reach the strategy.
### Turn bars into buy, sell, or hold decisions
Here is an EMA-crossover signal strategy. A repeated update inside the same
one-minute bar replaces that bar's current state, so a live feed correction does
not create a phantom second crossover.
```rust
use chrono::{DateTime, Utc};
use chrono_ta::indicators::{CrossAbove, CrossBelow, ExponentialMovingAverage};
use chrono_ta::Next;
use std::time::Duration;
#[derive(Debug, Clone, Copy, PartialEq, Eq)]
enum Decision {
Buy,
Sell,
Hold,
}
struct EmaCrossStrategy {
fast: ExponentialMovingAverage,
slow: ExponentialMovingAverage,
cross_above: CrossAbove,
cross_below: CrossBelow,
}
impl EmaCrossStrategy {
fn new() -> Result<Self, chrono_ta::errors::TaError> {
Ok(Self {
fast: ExponentialMovingAverage::new(Duration::from_secs(5 * 60))?,
slow: ExponentialMovingAverage::new(Duration::from_secs(20 * 60))?,
cross_above: CrossAbove::new(Duration::from_secs(60))?,
cross_below: CrossBelow::new(Duration::from_secs(60))?,
})
}
fn on_close(&mut self, timestamp: DateTime<Utc>, close: f64) -> Decision {
let fast = self.fast.next((timestamp, close));
let slow = self.slow.next((timestamp, close));
let pair = (fast, slow);
if self.cross_above.next((timestamp, pair)) {
Decision::Buy
} else if self.cross_below.next((timestamp, pair)) {
Decision::Sell
} else {
Decision::Hold
}
}
}
```
Feed the queried bars through the strategy:
```rust
let bars = query_bars(&reqwest::Client::new(), "SPY").await?;
let mut strategy = EmaCrossStrategy::new()?;
for bar in bars {
let close: f64 = bar.close.parse()?;
match strategy.on_close(bar.timestamp, close) {
Decision::Buy => println!("{} BUY SPY", bar.timestamp),
Decision::Sell => println!("{} SELL SPY", bar.timestamp),
Decision::Hold => {}
}
}
```
That loop is suitable for research, backtests, or signal generation. For a bot,
route a decision through a separately guarded Public adapter. Public accepts a
caller-supplied UUID as the idempotent order ID:
```rust
use serde_json::json;
use std::{env, error::Error};
use uuid::Uuid;
async fn submit_public_order(
client: &reqwest::Client,
symbol: &str,
decision: Decision,
) -> Result<Option<Uuid>, Box<dyn Error>> {
let side = match decision {
Decision::Buy => "BUY",
Decision::Sell => "SELL",
Decision::Hold => return Ok(None),
};
// Historical replay must never be able to satisfy this guard accidentally.
if env::var("ENABLE_PUBLIC_ORDER_SUBMISSION").as_deref() != Ok("I_UNDERSTAND") {
return Err("live Public order submission is disabled".into());
}
let access_token = env::var("PUBLIC_ACCESS_TOKEN")?;
let account_id = env::var("PUBLIC_ACCOUNT_ID")?;
let order_id = Uuid::new_v4();
let body = json!({
"orderId": order_id.to_string(),
"instrument": { "symbol": symbol, "type": "EQUITY" },
"orderSide": side,
"orderType": "MARKET",
"expiration": { "timeInForce": "DAY" },
"quantity": "1"
});
client
.post(format!(
"https://api.public.com/userapigateway/trading/{account_id}/order"
))
.bearer_auth(access_token)
.json(&body)
.send()
.await?
.error_for_status()?;
Ok(Some(order_id))
}
```
This is the final transport step, not a complete risk system. Before enabling
it, call Public's
[preflight endpoint](https://public.com/api/docs/resources/order-placement/preflight-single-leg),
process only unseen completed bars, persist the last bar timestamp and
serialized indicator state, reconcile the actual brokerage position, enforce
position/notional limits, and poll the returned order ID because placement is
asynchronous. Do not connect historical replay code directly to a live account.
Run the repository's provider-neutral version with:
```bash
cargo run --example ema_crossover
```
## Current-bar replacement
Streaming feeds often send several revisions of a bar before it closes. The
adaptive detector keeps those revisions from becoming several observations:
- windows shorter than five minutes use one-second buckets;
- intraday windows use one-minute buckets;
- windows of one day or longer use the library's daily-session gap rule.
Calling `next` twice inside the same bucket replaces the current observation
instead of advancing the indicator. Timestamps should therefore arrive in
nondecreasing order. This behavior is a core difference from upstream `ta`, not
an incidental optimization.
Indicators that operate on OHLCV bars accept an explicit `bucket_width`. This
makes the identity of a revisable live bar unambiguous instead of guessing its
cadence from the rolling window.
## Batch processing
`NextBatch` returns the same state transition as calling `next` repeatedly.
EMA and RSI use optimized batch implementations when no input would trigger
same-bucket replacement; other indicators use the trait's scalar fallback.
```rust
use chrono::{Duration as ChronoDuration, TimeZone, Utc};
use chrono_ta::indicators::RelativeStrengthIndex;
use chrono_ta::NextBatch;
use std::time::Duration;
let start = Utc.with_ymd_and_hms(2026, 9, 20, 0, 0, 0).unwrap();
let inputs = vec![
(start, 100.0),
(start + ChronoDuration::days(1), 102.0),
(start + ChronoDuration::days(2), 101.0),
];
let mut rsi = RelativeStrengthIndex::new(Duration::from_secs(14 * 86_400)).unwrap();
let values = rsi.next_batch(&inputs);
assert_eq!(values.len(), inputs.len());
```
The public `simd` module also exposes EMA, rate-of-change, reduction, rolling
mean, and rolling-standard-deviation primitives for callers that already own
contiguous slices.
## Indicators
| Trend and composition | Exponential Moving Average, Simple Moving Average, Rolling Sum, Lag / Value Ago, Cross Above, Cross Below |
| Momentum | Relative Strength Index, Rate of Change |
| Volatility | Bollinger Bands, Standard Deviation, Mean Absolute Deviation, True Range, Average True Range |
| Volume | Rolling VWAP, Anchored VWAP |
| Extrema and risk | Minimum, Maximum, Max Drawdown, Max Drawup |
The narrower catalog is intentional. Indicators present in upstream `ta`, such
as MACD, stochastic oscillators, and OBV, are not currently implemented
here. Do not select this crate on the assumption that every upstream indicator
is available.
`AverageTrueRange` is the arithmetic mean of true ranges inside an elapsed-time
window; it is not Wilder's observation-count recurrence. `RollingVwap` expires
contributions by elapsed time. `AnchoredVwap` accumulates until the caller invokes
`Reset::reset`. Both VWAP variants use typical price `(high + low + close) / 3`.
## OHLCV indicators
`DataItem` provides a validated OHLCV input, while the public `Open`, `High`,
`Low`, `Close`, and `Volume` traits let applications use their own bar types.
```rust
use chrono::{Duration as ChronoDuration, TimeZone, Utc};
use chrono_ta::indicators::{AverageTrueRange, RollingVwap};
use chrono_ta::{DataItem, Next};
use std::time::Duration;
let start = Utc.with_ymd_and_hms(2026, 9, 20, 14, 30, 0).unwrap();
let first = DataItem::builder()
.open(100.0)
.high(104.0)
.low(99.0)
.close(102.0)
.volume(1_000.0)
.build()
.unwrap();
let second = DataItem::builder()
.open(102.0)
.high(106.0)
.low(101.0)
.close(105.0)
.volume(1_500.0)
.build()
.unwrap();
let bucket = Duration::from_secs(60);
let mut atr = AverageTrueRange::new(Duration::from_secs(15 * 60), bucket).unwrap();
let mut vwap = RollingVwap::new(Duration::from_secs(15 * 60), bucket).unwrap();
assert_eq!(atr.next((start, first)), 5.0);
assert_eq!(atr.next((start + ChronoDuration::minutes(1), second)), 5.0);
assert!(vwap.next((start, first)).is_some());
```
## State and serialization
The optional `serde` feature serializes indicator state. Optimized derived
state is rebuilt when needed after deserialization, and the test suite covers
continuing an indicator after a round trip.
Serialized representations are an implementation detail, not a stable wire
format. Keep the crate version with persisted state and test migrations before
upgrading a long-lived store.
## Migrating from the old repository name
GitHub redirects the former `austin-starks/ta-rs-improved` URL, so dependencies
pinned to an existing commit continue to resolve. New dependencies should use
the `chrono-ta` package and URL.
To preserve existing `use ta::...` imports while moving to a new revision,
rename the dependency locally:
```toml
[dependencies]
ta = { package = "chrono-ta", git = "https://github.com/austin-starks/chrono-ta" }
```
The source imports can then remain unchanged even though the published package
is named `chrono-ta`.
## Development
```bash
cargo fmt --check
cargo test --all-targets --all-features
cargo test --doc --all-features
cargo doc --no-deps --all-features
cargo package --list
```
See [CONTRIBUTING.md](CONTRIBUTING.md) for defect reports, test expectations,
and pull-request scope. Security problems should be reported privately through
[SECURITY.md](SECURITY.md).
## Releases
Published versions are available on [crates.io](https://crates.io/crates/chrono-ta),
with API documentation built by [docs.rs](https://docs.rs/chrono-ta). The
release checklist in [CONTRIBUTING.md](CONTRIBUTING.md) treats the registry
upload as a deliberate, irreversible step after the exact commit passes CI.
## NexusTrade
`chrono-ta` powers time-windowed technical indicators in
[NexusTrade](https://nexustrade.io/), an AI-assisted platform for researching,
testing, optimizing, and deploying systematic trading strategies.
The fork's original RSI correction is described in
[this development article](https://nexustrade.io/blog/i-used-an-ai-to-fix-a-major-bug-in-a-very-popular-open-source-technical-indicator-library-20231223).
## License and upstream credit
Released under the [MIT License](LICENSE). `chrono-ta` is derived from
[Greyblake's `ta`](https://github.com/greyblake/ta-rs), created by Sergey
Potapov and its contributors. Austin Starks maintains this timestamp-aware fork.